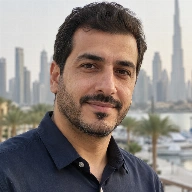
Fadel Abdulbaqi Al Ali will take over as chairman of Dubai Islamic Bank on 30 September 2026. The Central Bank of the UAE has signed off on the appointment. Mohammed Ibrahim Al Shaibani, the outgoing chairman, resigned from both the board and his leadership post for personal reasons. The change comes at a time when the UAE's banking sector faces close regulatory oversight, as shown in recent Emirates News Agency updates.
Al Ali is no stranger to the financial world. He has more than 30 years of experience in banking, investment, real estate, and hospitality. He currently chairs the Dubai Financial Services Authority and Majid Al Futtaim Capital. He also sits on the boards of the Commercial International Bank in Egypt and the Financial Stability Board. The bank's statement points to his leadership record. It fits with the UAE's push for strong corporate governance and financial stability under the Dubai Economic Agenda D33 and Vision 2031.
Strategic priorities and global reach
The board picked Al Ali for his track record and clear vision. They expect him to keep Dubai Islamic Bank at the top of global Islamic finance. The bank's strategy is built on strong governance and financial discipline. It aims to keep growing across the Middle East, Asia, and Africa. The National reports that DIB's international moves are watched closely as a sign of where Islamic finance is heading in the region.
Dubai Islamic Bank now serves more than 11 million customers. Its reach covers the UAE, Pakistan, Turkey, Indonesia, Kenya, Sudan, and Bosnia. The bank holds about $115 billion in assets. Its market value is over $18 billion. More than 12,000 employees work at 540 branches worldwide. The bank has bought a 25% stake in Turkey's TOM Group, expanded into Kenya, and rolled out digital banking in Indonesia and Pakistan. These steps match the UAE's goal to draw foreign investment and build stronger financial links across borders, as set out by the Ministry of Economy and the Dubai Media Office.
Leadership legacy and sector impact
Mohammed Ibrahim Al Shaibani led Dubai Islamic Bank through a period of growth and change. The board thanked him for his work. They credit him with making the bank stronger and helping it become a top Islamic financial group. Al Shaibani had just started a new three-year term before stepping down. That makes this leadership change even more notable, according to Argaam and other regional financial outlets.
Dubai Islamic Bank was the first fully integrated Islamic bank. It is now one of the most systemically important banks in the UAE. The takeover of Noor Bank was a turning point. It cemented DIB's lead in global Islamic finance. As reported earlier, competition among UAE banks is heating up. Banks are racing to lead in innovation, sustainability, and market reach.
With Al Ali stepping in, Dubai Islamic Bank looks set to push its strategy forward. The bank plans to use its size, strong governance, and global partnerships to keep growing. Digital transformation and market expansion remain top priorities. The Central Bank of the UAE and the Dubai Financial Services Authority will keep shaping the rules that guide these changes and support the sector's growth. The message is clear. Dubai Islamic Bank wants to stay ahead.